
6 Essential Steps to Build Credit Without Parental Help
Jun 02, 2026


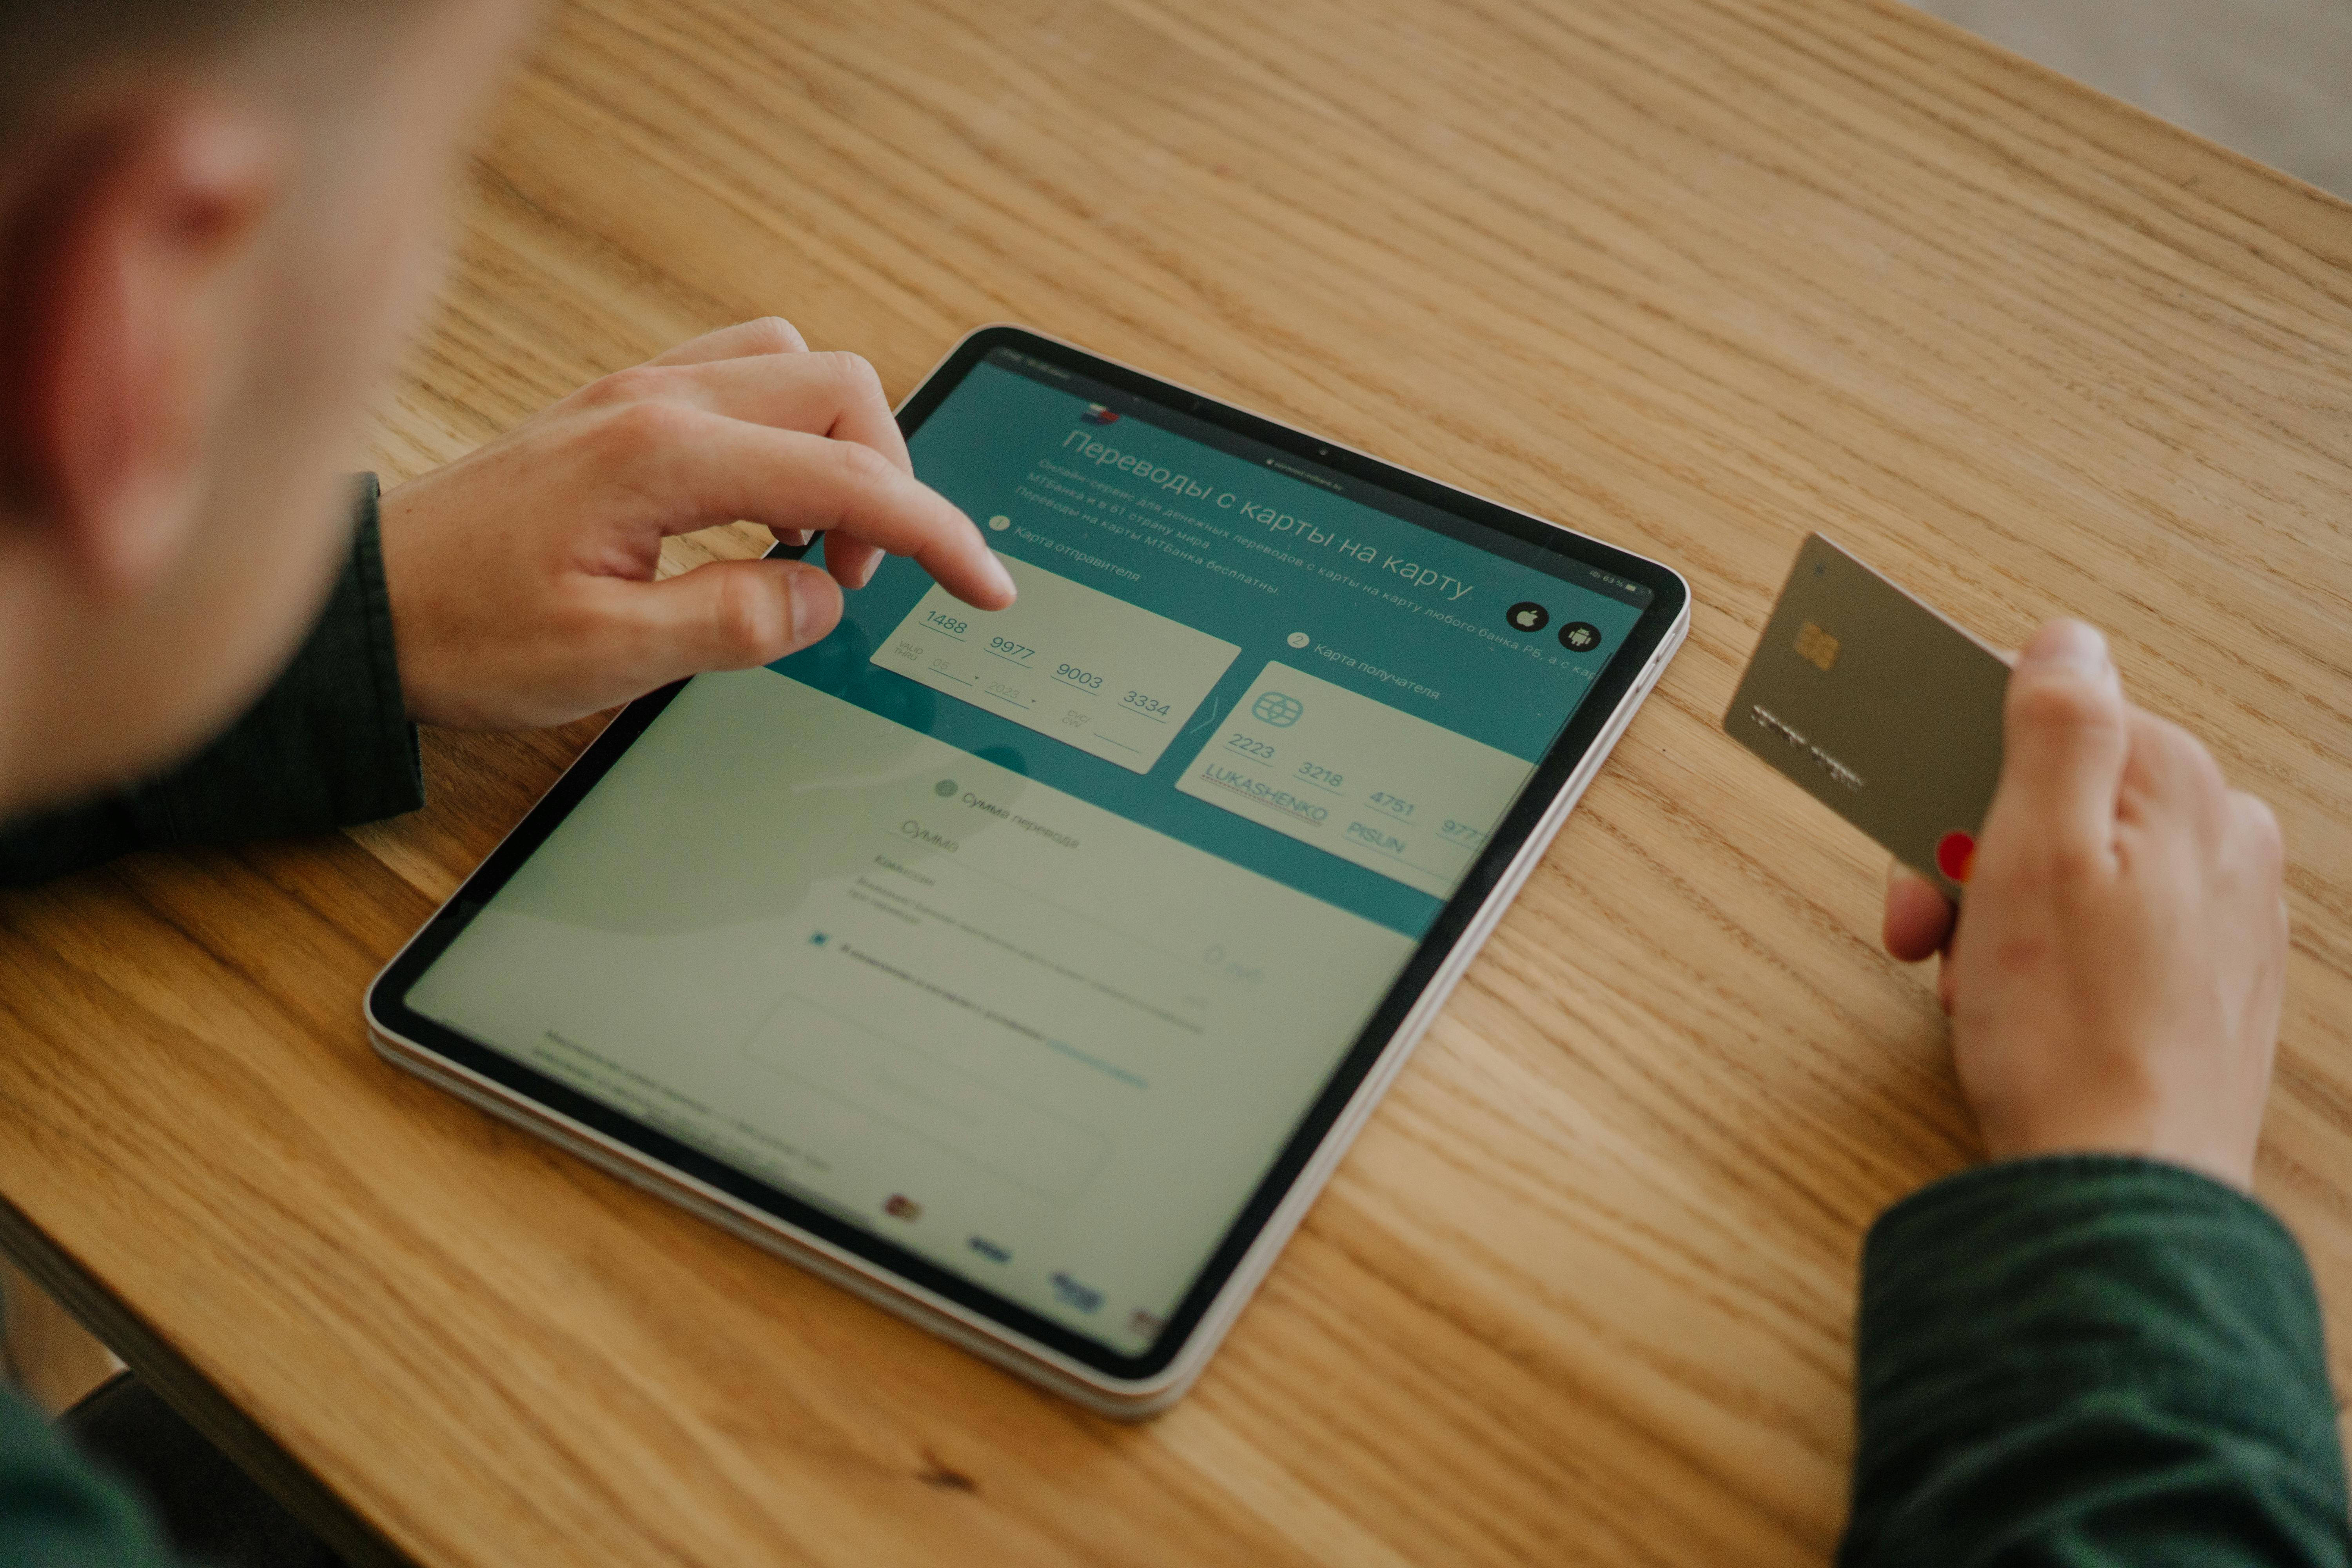
Credit cards that accept credit history from another country are available in the United States through issuer programs that evaluate an established overseas record alongside U.S. identity and income information. For eligible newcomers, the process can connect a foreign credit profile to a new U.S. card, subject to country coverage, documentation, issuer approval, and the card’s stated fees and APR. American Express explains its international-credit application process.
The key is choosing a card issuer that has a way to evaluate international information. Some applications use a cross-border credit-reporting service, while others rely on an existing relationship with the issuer. You still need to show that you live in the United States, can repay the account, and can verify your identity. The following steps explain how to prepare, compare products, and submit an application without overlooking important costs or review requirements. The CFPB describes the identity, address, and taxpayer information commonly collected for new credit accounts.
The clearest example is American Express’s newcomer process, which works with Nova Credit for certain personal-card applications. The published materials state that applicants from Australia, Canada, India, Mexico, and the United Kingdom may be able to use qualifying foreign credit history when applying for an American Express Personal Card. The issuer may request a manual review, and the final decision remains based on the complete application. American Express describes the countries and Nova Credit connection in its newcomer information.
This process does not transfer your foreign credit score into a U.S. credit score. Instead, the issuer receives information that can help evaluate your previous repayment record. Nova Credit says its Credit Passport product allows participating financial institutions to use consumer-permissioned international credit information when assessing applicants in the United States. Coverage depends on the applicant’s country, the available bureau data, and the financial institution’s participation. Nova Credit explains how its cross-border credit reporting works.
A second route is available to existing American Express primary cardholders moving to the United States. The issuer’s Global Card Transfer process asks for the existing account number and information such as a U.S. address, U.S. bank details, passport information, employment details, and a Social Security number or Individual Taxpayer Identification Number. The account must meet the issuer’s stated eligibility conditions, including being open and in good standing and having been held for at least 3 months. American Express lists the Global Card Transfer requirements.
Before starting an application, prepare documents that match the information entered on the form. A foreign credit history can support the review, but it does not replace U.S. identity and residence verification. The issuer may request additional documents when names, addresses, identification numbers, or account information cannot be confirmed electronically. American Express lists common personal-card application information.
Useful documents may include:
The exact document list varies by issuer and application channel. Documents should be current, readable, and consistent with the legal name used on the application. If a manual review is required, the issuer may request additional identification or address evidence before making a decision. The CFPB notes that card issuers may collect names, dates of birth, addresses, and taxpayer or other identification numbers.
Foreign credit history helps explain how you handled credit abroad, but the issuer also reviews repayment capacity. Applications commonly request annual income and its source. The card agreement should be reviewed for the purchase APR, annual fee, late-payment fee, foreign-transaction fee, balance-transfer fee, cash-advance fee, and any promotional period. The FDIC explains that APR represents the annual cost of credit and that card issuers must disclose important rate and fee information. Review the FDIC’s credit-card comparison guidance.
Credit cards generally do not have a fixed repayment term like installment loans. Interest can continue to accrue when a balance is carried from month to month. For an illustration, a $1,000 balance at a 24.99% annual percentage rate would create approximately $20.83 in monthly interest before considering daily-compounding details, fees, payments, or changes in the balance. Paying only the minimum can extend repayment substantially, while paying the statement balance by the due date can avoid purchase interest when the account’s grace-period rules are satisfied. The actual calculation depends on the issuer’s agreement and daily balance method.
A card with a lower APR but a $95 annual fee may cost more than a no-annual-fee card if the balance is small and the account is used infrequently. Conversely, a fee-bearing card may offer features that matter to a particular applicant. The important comparison is the total expected cost, not only the rewards or introductory offer. The FDIC lists common credit-card fees and explains why APR and promotional terms should be compared.
A card that evaluates foreign credit history can be useful when an applicant has a strong overseas record but little U.S. credit data. A secured card may be available to some applicants who cannot use foreign history, but it usually requires a refundable security deposit that commonly establishes the credit limit. A student card may consider enrollment and income information. Some issuers also permit an authorized-user relationship, although the account’s effect depends on the issuer’s reporting practices and account management.
The comparison should focus on approval requirements, annual fee, APR, foreign-transaction fee, deposit requirement, credit-limit policy, reporting to U.S. credit bureaus, and whether the application uses a soft or hard credit inquiry. Capital One explains that some international students may qualify for student or secured cards, even when they have limited U.S. credit history, although requirements differ by product. Read Capital One’s guidance for international students.
An international-history card and a secured card serve different purposes. The first may use information from the applicant’s prior country of residence; the second may rely more heavily on a deposit and the applicant’s current U.S. profile. Neither product removes the need to compare APR, fees, repayment rules, and credit-reporting practices. The FDIC recommends comparing credit-card terms before opening an account.
Use the issuer’s official application page and enter the information exactly as it appears on identity documents and financial records. If the application offers a prompt for an existing international relationship or foreign credit history, complete that section rather than submitting a standard application that omits relevant information. Keep a copy of the application details and the disclosures shown before submission. American Express provides its official card-application information requirements.
A fully completed application may receive an electronic decision, but manual review can take longer. American Express states in its newcomer material that some applications may require manual review and may receive a decision within 30 days of submission. Its Global Card Transfer page states that processing can take 7–10 working days and that required documentation may be requested. These timelines apply to the cited American Express processes, not to every issuer or card. See the issuer’s published newcomer and transfer timelines.
A full credit-card application can result in a hard inquiry. The CFPB explains that a hard inquiry appears on a credit report and may affect a credit score, while a soft inquiry does not affect the score. If an issuer offers prequalification, read the disclosure carefully to confirm whether it uses a soft inquiry and whether submitting the full application will create a hard inquiry. Review the CFPB’s explanation of hard and soft inquiries.
Once approved, review the account-opening disclosure, credit limit, due date, minimum payment, APR, and fees before making purchases. The account can help establish U.S. credit history only if the issuer reports account activity to U.S. credit bureaus. Confirm this point in the card agreement or by asking the issuer through an official account channel. Keep balances manageable and make at least the required payment by the due date.
A first U.S. card can create a foundation for future credit applications, but payment history and balances remain important after approval. Set payment reminders, monitor statements, and dispute unfamiliar transactions through the issuer’s documented process. The FDIC notes that cardholders should understand minimum payments, interest, fees, and protections connected with unauthorized transactions. Read the FDIC’s consumer guidance on credit cards.
Use only the issuer’s official website or a clearly identified, authorized application link. Be cautious of any service that promises approval because of a foreign credit score or demands an upfront payment before providing credit. The FTC warns that scammers may promise a credit card regardless of credit history and then request processing, insurance, or other fees before the account exists. Review the FTC’s advice on advance-fee credit offers.
A legitimate card application explains the issuer, fees, APR, privacy terms, and review process. It should not require payment to “unlock” approval or promise a specific credit limit. The FTC also advises consumers to avoid unexpected offers that request personal information or upfront fees in exchange for lower credit-card rates. See the FTC’s consumer alert about credit-card rate-reduction scams.
Yes, some issuer processes can evaluate qualifying foreign credit history, including the American Express newcomer process supported by Nova Credit for applicants from selected countries. Coverage, required information, and approval standards vary by issuer and product. The foreign record supports underwriting; it does not automatically become a U.S. credit score. American Express identifies the currently listed qualifying countries in its newcomer material.
There is no single minimum score for every card that accepts foreign credit history. The issuer may review overseas repayment data, U.S. income, residence, identification, existing U.S. credit information, and other application details. The card’s official eligibility criteria are more reliable than a general score estimate because underwriting standards differ by product. The CFPB explains that issuers set standards based on credit history and other application information.
Income requirements vary by issuer and card. Applicants should expect to provide annual income and its source, and the issuer may consider the information when assessing repayment ability. Do not include income that the application does not permit or count. American Express lists annual income and income source among personal-card application information.
A full application can produce a hard inquiry, which may appear on a credit report and may affect a credit score. A prequalification process may use a soft inquiry, but the issuer’s disclosure controls the result. Read the inquiry language before moving from prequalification to a complete application. The CFPB explains the difference between hard and soft inquiries.
Timing depends on the issuer, application completeness, identity checks, and whether manual review is needed. American Express states that some newcomer applications may receive a decision within 30 days, while its Global Card Transfer information gives a 7–10 working day processing estimate. Card delivery occurs after approval and any required documentation review. Review the issuer’s published process details.
Credit cards that accept credit history from another country give eligible newcomers a practical way to present an established overseas repayment record while beginning a U.S. credit profile. The strongest application is organized around the issuer’s country coverage, identity documents, U.S. address, income information, inquiry disclosure, APR, fees, and review timeline. Comparing the official terms before submitting a full application helps connect the right international-credit process with a manageable repayment plan.
Applicants can review official card disclosures, compare eligible products through established financial platforms, and use issuer prequalification when it is available and clearly identified as a soft inquiry. After approval, on-time payments, controlled balances, and careful statement review determine how the new account functions over time. NerdWallet, Bankrate, and LendingTree provide comparison tools, while the issuer’s own agreement remains the controlling source for final terms.
Many people experience stress when medical bills start to pile up, especially if costs come as a surprise. You can ease this burden by taking straightforward actions...
Aug 22, 2026
Taking initiative early in your career helps you notice opportunities to help and guide those around you. You can start acting like a leader even without a formal title...
May 18, 2026
Selecting an employee benefits package often influences your financial well-being well into the future. Starting a new position brings a wave of new information,...
May 23, 2026
Many people feel a rush of nerves when they enter a room full of candidates, all eager to impress. The challenge lies in making a positive impression while showing...
May 27, 2026
Sharing a home with friends often brings concerns about splitting bills and handling chores. When everyone understands their responsibilities from the start, daily life...
Jun 06, 2026
Balancing your finances carefully opens up plenty of room for enjoyment and personal interests, even when money feels limited. You can savor days out, explore new...
Jun 10, 2026

Beginning therapy on your own may seem unfamiliar and a bit overwhelming at first. Questions often arise about how to get started, which methods will suit you best, and...
Jun 15, 2026
Life sometimes throws unexpected challenges our way, making it tough to find your footing again. Taking small, consistent steps can make the process of recovery feel...
Jun 21, 2026
Finding ways to stay active while managing expenses can seem challenging, but you can achieve your fitness goals without spending a lot of money. You don't have to rely...
Jun 24, 2026
Crafting a memorable presence begins with recognizing the qualities that set you apart from others. Your unique combination of skills, core values, and life experiences...
Jun 28, 2026
Preparing for a virtual performance review often brings a mix of anticipation and nerves. You aim to highlight your accomplishments while making a strong impression on...
Jul 01, 2026
Starting out in a new profession often brings a mix of excitement and uncertainty, as you try to figure out which direction to take. The choices you make early on can...
Jul 05, 2026
Many people want to make the most of a night out while still keeping their finances on track. You can have fun and still make steady progress toward your financial goals...
Jul 10, 2026
Many people start a side project that grows from a personal interest or talent—like designing hand-painted mugs after work, offering math help on *TutorMe* , or picking...
Jul 21, 2026